
Homeowner guide
What to do after home damage before filing an insurance claim
A safety-first checklist for protecting people and property, documenting damage, and preparing clear questions for your insurer after a home incident.
Published October 3, 2026
By the HomeFAQ Editorial Team · Reviewed for accuracy.
https://homefaq.com/home-insurance/what-to-do-after-home-damage-before-filing-an-insurance-claim/
Printing is unavailable. Use your browser’s Print command.
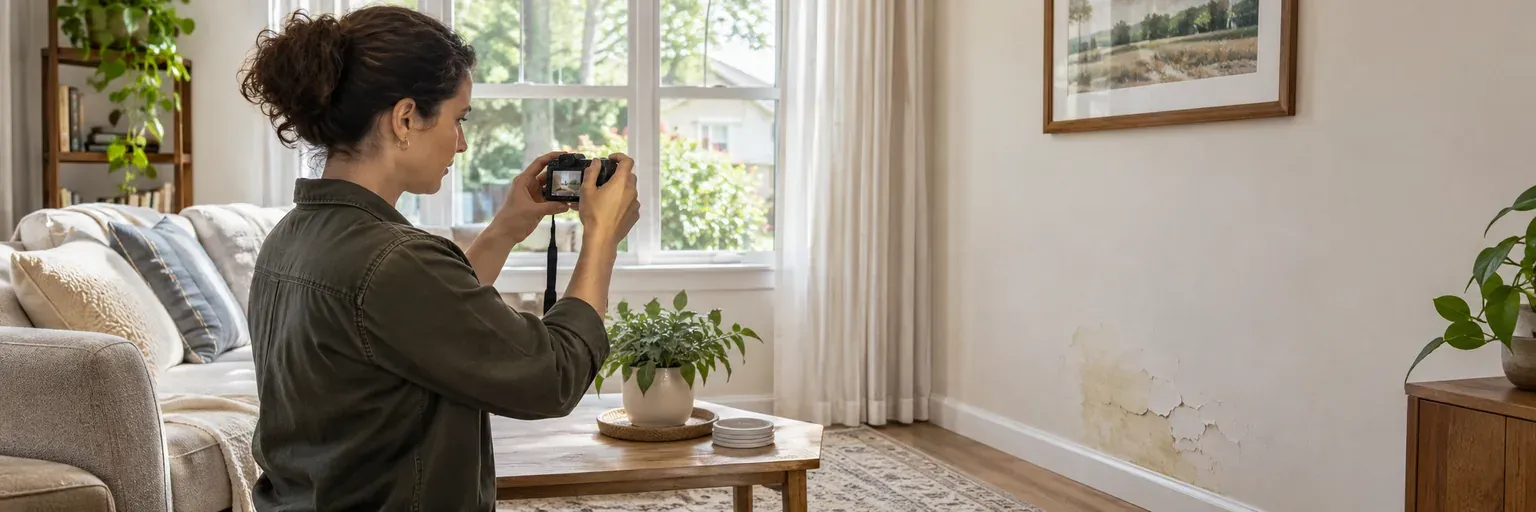
After home damage, protect people first, stop further damage only when it is safe, and make a simple dated record before the scene changes. Contact emergency services for an immediate danger, and contact qualified help for hazards you cannot safely control. Then read your policy’s reporting instructions or call the insurer to understand its process. This is not advice about whether to file a claim: coverage, deductibles, deadlines, and claim consequences depend on the policy, the facts, and state law.
1. Get people away from an active hazard
Call 911 or the appropriate local emergency number for fire, a suspected gas leak, downed power lines, an unstable structure, or an immediate threat to life. Do not enter standing water if electrical power could be present, climb onto a damaged roof, or handle damaged electrical equipment. If flooding, sewage, smoke, or another contamination hazard is involved, follow local emergency and public-health instructions before treating it as a cleanup project.
From a safe location, note the date and time, what happened, and whether the condition is still changing. That short record can be useful later, but it should never delay evacuation, emergency response, or a necessary safety step.
2. Limit additional damage without making unsafe repairs
If it is safe and within your ability, take reasonable temporary steps to prevent more damage, such as moving dry belongings away from an active leak or covering an opening after wind damage. Keep receipts and photos for emergency supplies or work. FEMA advises disaster survivors to document damage and keep receipts for cleanup and repair expenses.
Do not perform work that requires entering a dangerous area, handling electrical systems, shutting off unfamiliar gas equipment, removing a tree from a structure, or opening walls or ceilings. Ask the insurer what temporary-protection steps it wants documented and whether it has instructions for emergency mitigation. A necessary temporary measure is not proof that a later claim will be covered.
3. Document what you can safely see
Before cleanup or repair changes the scene, take wide photos of each affected room and closer photos of visible damage, labels, and damaged belongings. A short video walkthrough can add context. Keep original files if possible and write down the date, time, location, and what you observed. Do not move unsafe materials just to get a better photo.
Make a simple list of affected areas and belongings. Include the item, room, approximate age or purchase information if known, and any available receipt, serial number, or prior photo. Avoid guessing at a cause, repair cost, or coverage outcome. If an item must be discarded for health or safety reasons, photograph it first only if doing so is safe, and retain any disposal record.
4. Start one factual record folder
Use a paper folder, a secure cloud folder, or both. Put these items in it as they become available:
- Dated photos and video, plus a timeline of what happened and what changed.
- Receipts, invoices, work authorizations, estimates, and temporary-protection records.
- Names, phone numbers, dates, and short factual notes from conversations with the insurer, adjuster, emergency responder, or contractor.
- The declarations page, relevant policy pages, and any claim instructions the insurer provides.
- Written scopes that distinguish emergency mitigation from permanent repair work.
The National Association of Insurance Commissioners recommends documenting damage, keeping receipts, and retaining communications after a disaster. Keep sensitive policy and financial information in a secure place; do not post claim details or policy documents publicly.
5. Contact the insurer for process information
Use the claim-reporting contact listed in your current policy, insurer app, or official website. Explain the facts you know, ask what immediate documentation it needs, and ask how it wants estimates, receipts, and photos submitted. Write down any claim number and the name of the person you spoke with.
Do not rely on a contractor, neighbor, or social-media post to interpret your policy. An insurer or licensed agent can explain the reporting process and policy documents, but only the policy and the facts determine how a particular loss is handled. For general consumer help or a complaint process, your state insurance department may be a useful official resource; it cannot provide legal advice or decide your individual coverage.
6. Be careful when choosing emergency or repair help
Urgent conditions can attract high-pressure offers. The Federal Trade Commission recommends checking a contractor’s identity and references, getting written estimates, reading the contract, and avoiding pressure to sign immediately. Ask a company to state what it will do now, what it will not do, who will perform the work, and how changes will be approved in writing.
Do not sign an assignment, authorization, or repair contract you do not understand. Do not sign over insurance benefits or agree to a price simply because someone says the insurer requires it. If time-sensitive mitigation is needed, ask for a written description of the emergency work, equipment, rate or pricing basis, and any customer responsibility before authorizing work when circumstances allow.
7. Prepare for the next conversation
Before you speak with an adjuster or a repair professional, gather your timeline, photos, receipts, policy declarations page, and a list of open safety or moisture concerns. Ask for written explanations of any requested documents, inspection findings, scope changes, or deadlines. Keep emergency mitigation, inspection, and rebuilding scopes separate so you can see what each covers.
If you need help comparing policies after the immediate situation is stable, read how to review your home insurance policy before renewal. For a future quote comparison, use our guide to comparing home insurance quotes. Neither guide determines what an existing policy covers.
Questions to ask your insurance representative
- What immediate safety, temporary-protection, and documentation steps does my policy’s claim process ask me to take, and where are those instructions written?
- How should I submit photos, receipts, and repair or mitigation estimates, and what claim number should I put on each record?
- Which deadlines, inspections, or written authorizations should I track before emergency work or permanent repairs move forward?
Sources
- Federal Emergency Management Agency, How to Document Damage and Begin Cleanup After a Disaster — safety, documentation, and cleanup-record guidance; accessed October 3, 2026.
- National Association of Insurance Commissioners, What to Do After a Disaster — insurer communication, receipts, and records guidance; accessed October 3, 2026.
- Federal Trade Commission, Working with Home Improvement Contractors — contractor-selection and written-contract guidance; accessed October 3, 2026.
- National Association of Insurance Commissioners, State Insurance Departments — official state insurance-regulator directory; accessed October 3, 2026.
Be ready for the conversation
3 questions to ask your insurance agent
- 1What dwelling-rebuild estimate, deductible choices, and property facts did you use for this quote?
- 2Which endorsements, exclusions, and separate peril deductibles make this quote different from my other quote?
- 3What can change this premium or eligibility at renewal, and where is that explained in the policy documents?
Keep planning
Related home insurance guides
How to compare home insurance quotes on matching coverage
Compare home insurance quotes by matching limits, deductibles, endorsements, exclusions, settlement terms, and quote dates.
How to review your home insurance policy before renewal
Review your home insurance policy before renewal by checking limits, deductibles, endorsements, exclusions, and your home inventory.
Home insurance terms homeowners should know
Plain-English definitions for the policy words you may see in a homeowners insurance quote, declarations page, claim, or renewal packet.